Originating since 2008 · nearly 2,000 loans closed
Your Louisville mortgage broker. Helping buyers, homeowners, and investors throughout Kentucky.
I compare conventional, jumbo, and specialty financing across a network of 200+ lenders. From choosing a loan structure to working through underwriting and closing, I manage the details with you.
No credit check for an initial conversation
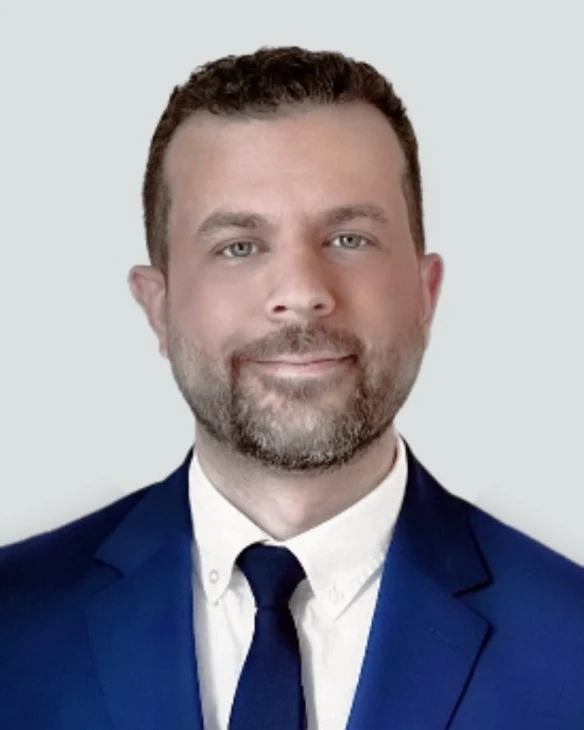
Ryan Miles Mortgage Broker · NMLS #112627
since 2008
network
How this works
You shouldn't have to shop lenders yourself.
I compare lenders and loan programs around your goals, budget, and timing. Then I walk you through the payment, the upfront costs, and the trade-offs so you can decide which option fits.
01
Tell me what you're working with
We start with what you're buying or refinancing, your budget, and your timing. I'll ask about your income, savings, and credit so I can narrow the options.
02
I compare options across my lender network
Rate is one variable. Fees, mortgage insurance, the program, and how long you plan to keep the house all change the real cost. I compare all of it and bring back the options that fit.
03
You pick, and I run it to closing
Once you choose, the process is mine to manage. You'll hear from me when there's something to decide, and you can reach me when there isn't.
Loan programs
Mortgage options for buying, refinancing, and investing.
From conventional and jumbo loans to DSCR, bank statement, and other non-QM options, I help you compare financing for your home, your business income, or your investment plans.
Kentucky down payment assistance
You may not need to save the whole down payment yourself.
I offer options to help with the down payment and closing costs, including grants that don't require repayment. I also have down payment assistance programs that pair with an FHA loan in Kentucky, a conventional loan, and in the right areas a USDA loan in Kentucky, and other first mortgage types. I'll explain the specific options when we talk.
Income and purchase-price limits apply, and they change by program and by county. Checking takes a few minutes, and it's worth doing before you fall in love with a house.
Ask about down payment assistance if any one of these sounds like you
- You have steady income but not much saved
- You're buying your first home, or your first in a while. Many of my programs don't require you to be a first-time buyer, though
- You assumed you earn too much to qualify. Some of the lenders I work with have no income limit, or one well above the standard limits
- You're buying in Shelby, Bullitt, Oldham, Nelson or Hardin County, where prices and program limits often line up well
- You want to compare a smaller down payment with keeping more cash in reserve
These are just a few examples. Down payment assistance is more widely available than most people think, so ask even if none of these fit.
The backing behind the broker
A local broker, with a national company behind me.
I work with Sweet Water Home Lending and have access to a network of more than 200 lenders. That range lets me compare financing for purchases, refinances, and investment properties, including loans that call for a specialty program.
Where I lend
Louisville, and the counties around it.
I work with buyers and homeowners throughout Louisville and the surrounding communities. In-person meetings are welcome. Call or text me and we'll set up a time to sit down.
Buying in Lexington or elsewhere in Fayette County? Here's how I work as a mortgage broker in Lexington.
About Ryan
Local roots, and a straightforward approach.
I was born and raised in Louisville and have been originating mortgages since 2008. I've closed nearly 2,000 loans across changing markets and lending programs.
Today I work with homebuyers, homeowners, self-employed borrowers, and real estate investors. My job is to compare the options, explain the trade-offs, and manage the financing from the first conversation through closing.
Common questions
The things people ask first.
What are mortgage rates in Louisville right now?
There's no one rate to quote. What you're offered depends on your credit profile, down payment, property type, loan program and how the loan is structured, and two lenders can look identical on paper while pricing very differently. As a broker, I compare your actual scenario with lenders in my network instead of reading one bank's rate sheet. The useful answer takes a short conversation.
How much money do I need to buy a house in Kentucky?
Often less than people expect. Conventional loans start at 3% down, FHA at 3.5%, and both USDA and VA can be zero down for eligible buyers. I also work with down payment assistance programs in Kentucky that can cover much of what's left. Plan for closing costs on top, though seller and lender credits often offset them.
Do I have to be a first-time buyer to use down payment assistance?
Not always. Several assistance programs define a first-time buyer as someone who hasn't owned a home in the last three years, and some have no first-time requirement at all. Ask before you assume you're excluded.
Why use a mortgage broker instead of going straight to a bank?
A broker gives you access to multiple lenders and loan programs through one point of contact. I compare rates, fees, mortgage insurance, and loan structure around your plans. That matters whether you're buying with strong credit, refinancing, documenting business income, or financing an investment property.
No credit pull · No obligation
Let's talk about your mortgage plans.
Tell me what you're buying or refinancing, your timing, and the questions you want to work through. I'll review the details and contact you about the next step.
🔒 Nothing on this form touches your credit. No Social Security number, no pay stubs, no application. Just enough for me to follow up with you. Equal Housing Opportunity. Ryan Miles, NMLS #112627 · Coast2Coast Mortgage, LLC, NMLS #376205.